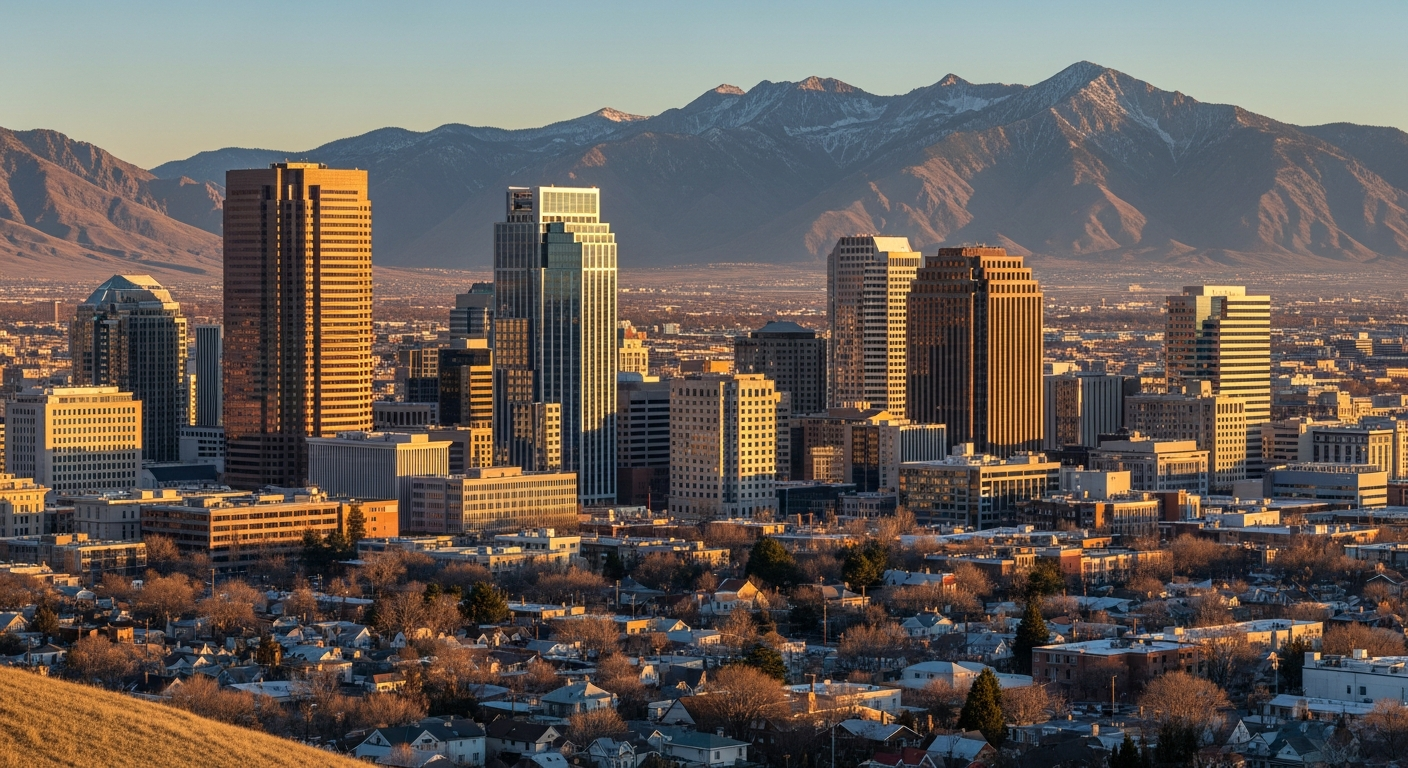
The SLC Market Thesis
Salt Lake City did not quietly become expensive. It sprinted there.
For most of its modern history, the Salt Lake metro was celebrated as one of the most livable and attainable mid-size cities in the United States. Low cost of living, proximity to world-class outdoor recreation, a growing technology sector anchored by Silicon Slopes, and a relatively young, well-educated population all added up to a compelling case for planting roots here. Word got out.
Between 2019 and 2023, Utah's capital metro saw some of the steepest home price appreciation in the country. Remote workers from San Francisco and Seattle discovered they could afford the Utah lifestyle on California salaries. Major tech companies opened offices or expanded existing footprints along the Wasatch Front. The population of the greater Salt Lake metro has been growing steadily, and housing supply, though Utah has built more than most states, has consistently struggled to keep pace with demand.
The result is a city that, for a solo first-time buyer earning a median income, is now genuinely hard to enter. Median home prices in Salt Lake City proper have climbed well above what a single earner making a good living can comfortably service on a conventional mortgage. And yet rent for a two-bedroom apartment in the valley has risen to a point where staying a renter is not a comfortable default either.
That tension, between unaffordable solo ownership and expensive renting, is exactly where co-ownership becomes the most logical answer.
Salt Lake City is not just a place where co-ownership can work. It is a city where the market conditions, the demographics, the outdoor-driven lifestyle that pulls in roommates and friend groups, and the long-term economic trajectory make co-ownership a genuinely compelling ownership strategy for people who want to be here for the long run.
Utah Real Estate Law: What Co-Buyers Should Know
Utah is a relatively straightforward state for co-buyers. The legal landscape does not impose unusual restrictions on multiple unrelated buyers purchasing a primary residence together, and the LLC structure that Rhome uses to hold co-owned properties is well-established and widely recognized under Utah law.
A few things are worth understanding if you are considering co-ownership in Utah.
Title options in Utah. Utah recognizes joint tenancy, tenancy in common, and LLC ownership as valid ways to hold real property. Tenancy in common is the most flexible for co-buyers with unequal shares, since each owner holds a distinct, inheritable interest. Joint tenancy includes a right of survivorship, meaning one owner's interest automatically passes to the surviving owner(s) at death. Rhome uses an LLC structure rather than either of these, which provides cleaner governance, liability protection, and a formal governance agreement.
LLC formation in Utah. Utah has a straightforward LLC formation process administered through the Utah Division of Corporations. Formation fees are modest, and the state's LLC statutes provide solid protections for members. An LLC formed to hold a co-owned primary residence can define ownership percentages, management responsibilities, and exit procedures through its governance agreement, which is exactly what Rhome prepares for each group.
Property taxes and the primary residence exemption. Utah offers a primary residence exemption that reduces the taxable value of owner-occupied property. Co-owners living in the home as their primary residence generally qualify for this exemption on their share of the property. This is a meaningful benefit that renters do not have access to.
Utah has no state income tax on mortgage interest deductions at the state level in the same manner as federal. Co-owners can each deduct their share of mortgage interest on their federal returns, and Utah's state income tax structure follows federal adjusted gross income as a starting point, so the federal deduction has downstream effects on state liability as well. Consult a tax professional for guidance specific to your situation.
Rhome works with legal and tax professionals familiar with Utah law to ensure every co-ownership structure is correctly formed and documented.
Key Neighborhoods for Co-Buyers
Salt Lake City and its surrounding communities offer a range of neighborhoods that suit different buyer profiles and budgets. Here are four areas where co-buyers are finding strong opportunities.
Sugar House. Sugar House is one of Salt Lake City's most beloved urban neighborhoods, and for good reason. The area has walkable commercial corridors, independent restaurants, coffee shops, parks, and close access to public transit and the 9-Line rail. Homes in Sugar House tend to run in the higher end of the city's price spectrum, with many single-family homes and bungalows priced between $550,000 and $750,000. For co-buyers who want genuine urban walkability and neighborhood character, Sugar House delivers, and splitting the price makes it accessible.
9th and 9th. The 9th and 9th neighborhood sits adjacent to Sugar House and shares its walkable, neighborhood-business character. It has one of the city's most distinctive commercial strips and a mix of older craftsman bungalows and renovated mid-century homes. Prices are competitive with Sugar House, and the area draws professionals who want proximity to downtown without living in a high-rise. Co-buyers who already share a social scene in this part of the city often look here first.
Millcreek. Millcreek, which became its own incorporated city in 2016, sits just east of Salt Lake City proper and offers a suburban feel with strong neighborhood identity and good access to the canyons. The Millcreek area has a wide range of housing stock, from older ranch-style homes to newer construction, with prices typically ranging from the mid-$400,000s to the $700,000s depending on size and proximity to the canyon. For co-buyers who prioritize outdoor access, Millcreek is a serious option.
South Jordan. South Jordan is one of the fastest-growing communities in the Salt Lake valley, positioned in the southwestern part of the metro with easy access to I-15 and significant employment centers in the south valley tech corridor. Homes tend to be newer here, with many built in the last decade, and the area offers strong value relative to closer-in neighborhoods. Three- and four-bedroom homes can often be found in the $480,000 to $650,000 range, making it particularly suited to co-buyer groups of three or four people looking to maximize space per dollar.
Utah Housing Corporation Programs
Utah Housing Corporation (UHC) is the state's housing finance agency, and it administers several loan and assistance programs that may benefit co-buyers in Salt Lake City and across the Wasatch Front.
Score Loan Program. UHC's flagship homebuyer loan program offers below-market interest rates on FHA, VA, and conventional loans for eligible borrowers. The Score loan is specifically aimed at first-time homebuyers and requires completion of a homebuyer education course. Income limits and purchase price caps apply and vary by county.
Down Payment Assistance (DPA) Loan. UHC offers a second mortgage to cover down payment and closing costs for buyers using a UHC first mortgage. The DPA loan is structured to be deferred, with no monthly payments required, and becomes due when the property is sold, refinanced, or paid off. For co-buyers where at least one person qualifies as a first-time homebuyer, this can meaningfully reduce the upfront cost.
Home Again Loan. The Home Again program is for repeat buyers or those who do not qualify as first-time buyers under federal definitions. It offers competitive rates and can be paired with UHC's down payment assistance products.
NoMI Loan. UHC also offers a conventional loan option with no private mortgage insurance requirement, which can lower the monthly carrying cost for buyers who qualify. This is worth exploring alongside FHA options, depending on credit scores and down payment amounts within the group.
Because Rhome co-ownership groups often include at least one first-time homebuyer, several of these programs may be available to your group. A Rhome advisor will walk through which programs fit your group's specific profile and how assistance programs interact with the co-ownership structure.
FHA Co-Buying Math in SLC
FHA financing is the default path for most Rhome co-ownership groups. FHA loans allow multiple co-borrowers who each occupy the home as a primary residence, and they require only a 3.5% down payment on the total purchase price. That combination makes the math work for buyers who are ready to own but not sitting on a large pile of cash.
Here is how the numbers look on a $500,000 Salt Lake City home with two co-buyers and equal ownership splits:
- Total purchase price: $500,000
- FHA down payment (3.5%): $17,500
- Per co-buyer: approximately $8,750 each
- Estimated monthly mortgage (30-year fixed at current rates, approximate): approximately $3,000 to $3,200
- Per co-buyer: approximately $1,500 to $1,600 per month
- Property taxes, insurance, and HOA (varies): approximately $500 to $700 per month total
- All-in monthly cost per co-buyer: approximately $1,750 to $2,000
For comparison, a two-bedroom apartment in Salt Lake City currently rents for roughly $1,400 to $1,900 per month depending on neighborhood and amenities. A co-buyer's monthly share of a primary residence purchase is competitive with renting, with the critical difference that the monthly payment builds equity rather than going to a landlord.
With three co-buyers, the numbers become even more compelling:
- Down payment per person (three-way split): approximately $5,833
- Monthly mortgage share: approximately $1,000 to $1,067
- All-in monthly cost per person: approximately $1,175 to $1,400
The equity-building dynamic matters a great deal in a market like Salt Lake City. Even in a slower appreciation environment, owners capture gains that renters do not. And in a market with the long-term fundamentals of the Wasatch Front, that equity accumulation has historically been meaningful.
Closing costs for a $500,000 purchase typically run between $8,000 and $15,000, depending on lender, negotiated seller contributions, and specific circumstances. These are split among co-buyers as well, though the exact split depends on the ownership arrangement.
What Makes SLC Uniquely Suited to Co-Ownership
Not every city is equally suited to co-ownership. Salt Lake City sits at a rare intersection of factors that make the model not just viable, but genuinely smart.
A young, highly mobile population. Utah has one of the youngest median population ages of any state in the country. Salt Lake City draws young professionals from within Utah and from elsewhere, and the city has a deep culture of shared living. It is common for people to move to SLC for a job or for the mountains and quickly build a circle of close friends and colleagues. That social fabric is the raw material of co-ownership groups.
The outdoor lifestyle creates strong co-habitation patterns. People who ski, trail run, mountain bike, and climb together often also live near each other. The proximity to world-class recreation at Big and Little Cottonwood Canyons, Brighton, Snowbird, and dozens of trails within minutes of the city creates a social culture built around shared experiences. That culture extends naturally into wanting to live near each other, and co-ownership formalizes that into an ownership stake.
Significant price appreciation over time. The Wasatch Front has consistently been one of the stronger long-term appreciation markets in the American West. Silicon Slopes continues to grow, with companies like Adobe, Qualtrics, Domo, and dozens of mid-size tech firms employing tens of thousands of workers in the greater SLC metro. Population growth in Utah has outpaced most states for over a decade. The structural tailwinds for home values are real.
The price-to-income gap is acute. Median home prices in Salt Lake City have risen significantly faster than median incomes over the past decade. Solo ownership for a median-income earner has become difficult. That gap is the core problem co-ownership solves, and it is sharply present in SLC.
Rental costs are high and climbing. Salt Lake City rents have increased substantially, and the rental market remains competitive. Renters are spending serious money every month with no path to equity. The case for getting off the rental treadmill is strong.
Taken together, these factors make Salt Lake City one of the most compelling markets in the Mountain West for the co-ownership model. The people are here, the social infrastructure is here, the economic rationale is clear, and the long-term fundamentals favor buyers.
How Rhome Works in Salt Lake City
Rhome is not a lender or a landlord. Rhome is the structure and the platform that makes co-ownership work cleanly.
When two to four buyers decide they want to purchase a primary residence together in Salt Lake City, Rhome sets up an LLC to hold the property. Each co-buyer owns a share of that LLC corresponding to their agreed ownership percentage. The LLC holds the title, and each co-buyer's rights and responsibilities are defined in a custom governance agreement.
Rhome then helps the group secure FHA financing. Because FHA loans permit multiple co-borrowers who will each occupy the home as their primary residence, the structure qualifies without requiring any one person to fund the entire down payment. Each person on the mortgage is individually underwritten, and all qualifying incomes are considered.
The governance agreement Rhome prepares covers how monthly costs are divided, how decisions about the property are made, what maintenance reserve contributions look like, what happens when someone wants to sell their share, and how disputes are resolved. The agreement is specific to each group, legally binding, and designed to prevent the ambiguity that causes conflict.
Once the purchase is complete, you close on the home, move in, and live your lives. Rhome stays in the picture to help facilitate major decisions, coordinate eventual exits, and ensure the co-ownership relationship stays healthy over time.
The path to getting started is straightforward. You identify your co-buyer or co-buyers, apply together through Rhome's platform, and a Rhome advisor walks you through qualification, program options, neighborhood selection, and offer strategy. The platform supports you from first conversation through closing and beyond.
If you are renting in the Salt Lake valley today and spending serious money every month on rent with no equity to show for it, co-ownership is worth a serious look. The mountain view is the same whether you rent it or own it. The difference is what you are building toward.
Frequently Asked Questions
Do all co-buyers have to live in the Salt Lake City home?
Yes. Rhome co-ownership is built entirely on primary residence use. Every co-buyer must live in the home as their primary address. No subleasing, no short-term rentals, and no absentee co-owners are permitted. This is a core requirement of the FHA financing structure and of Rhome's model.
How does the FHA down payment split work with multiple buyers in Salt Lake City?
FHA loans require a minimum down payment of 3.5% of the purchase price. That total is divided among co-buyers according to their ownership shares. On a $500,000 Salt Lake City home, the total FHA down payment is $17,500, which splits to $8,750 per person for two equal co-buyers. With three buyers, each person contributes roughly $5,833. The structure scales, and every buyer is individually underwritten.
Can co-buyers combine their incomes to qualify for a larger mortgage in Utah?
Yes. Each co-buyer is individually underwritten, and all qualifying incomes are combined for the purpose of loan qualification. This is one of the most meaningful advantages of co-ownership: two or three people with solid but ordinary incomes can qualify for a mortgage that none of them could access alone.
Can co-buyers in Salt Lake City use Utah Housing Corporation programs alongside Rhome?
Several Utah Housing Corporation loan products are FHA-compatible and may be available to first-time buyers within a co-ownership group. Program eligibility depends on individual income, credit, and first-time buyer status. A Rhome advisor can help you understand which programs your group qualifies for and how to layer them with your co-ownership structure.
What happens if one co-buyer wants to sell their share or move out?
Rhome structures the co-ownership through an LLC with a formal governance agreement that defines exit provisions, buyout rights, and transition procedures from day one. You are not locked in with no path forward. The agreement gives every co-buyer a clear, legally documented process for eventual changes in circumstances.