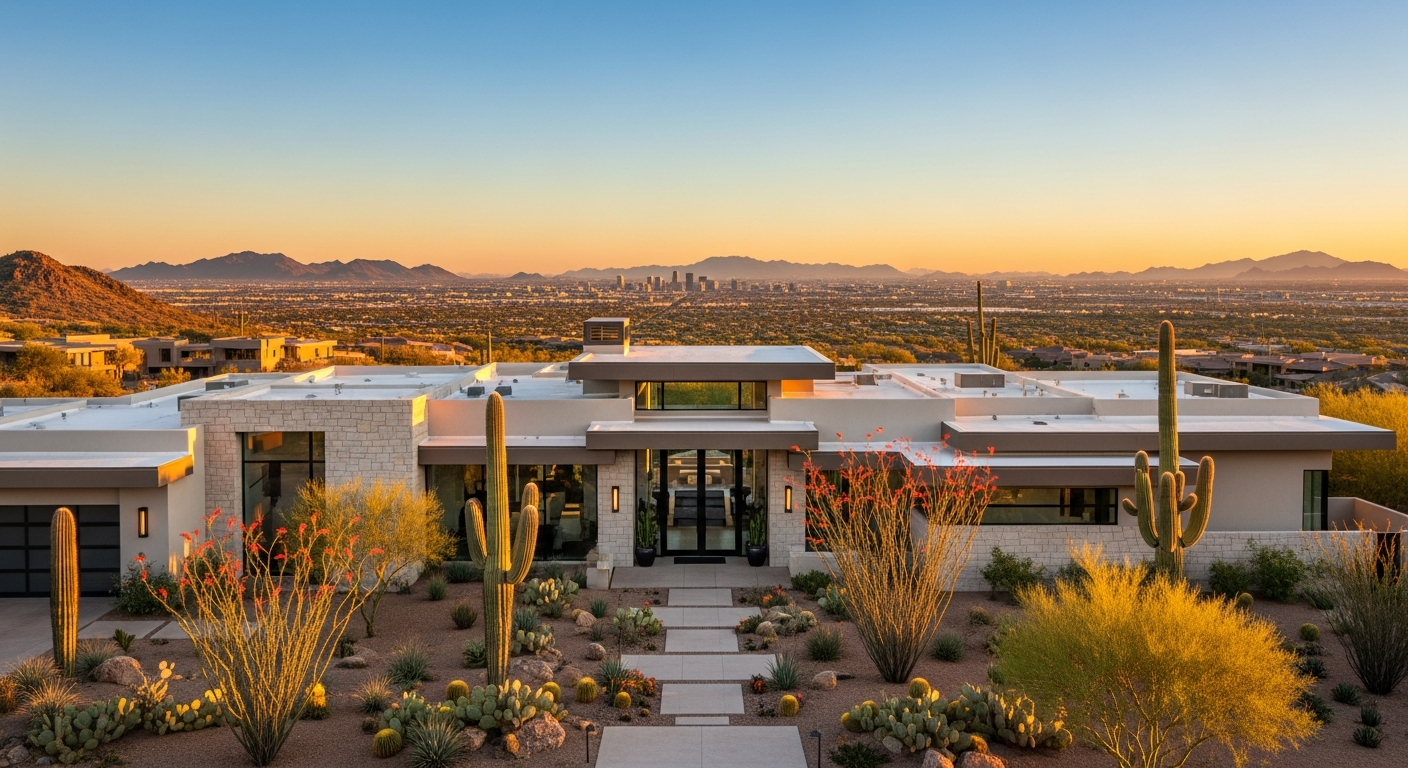
Phoenix is not a small market having a growth moment. It is the fifth-largest city in the United States, the anchor of a metro area that stretches from Scottsdale to Surprise and from Peoria to Gilbert. More people moved to the Phoenix metro over the past decade than to almost any other region in the country. They came for the weather, the jobs in semiconductor manufacturing and technology, the relative cost of living compared to Los Angeles and Seattle, and something harder to quantify: the sense that the Valley was still a place where you could actually build a life.
That last part has become more complicated. Phoenix home prices roughly doubled between 2020 and 2023, and while the market cooled somewhat from its peak, prices have largely held. Median home values across the Phoenix metro now sit in the $400,000 to $420,000 range, with premium areas pushing well past $700,000 and even entry-level communities an hour from downtown requiring buyers to show up with serious purchasing power. For someone earning $65,000 a year, a solo purchase in the Valley requires a near-perfect financial picture: excellent credit, minimal debt, a large down payment, and monthly payments that consume an uncomfortable share of take-home pay.
Co-ownership does not change those underlying numbers. It divides them.
Why the Entire Valley Matters
When people say "Phoenix," they often mean a much larger geography. The greater Phoenix metro, officially called the Phoenix-Mesa-Chandler Metropolitan Statistical Area, covers roughly 14,600 square miles and includes cities that function as fully independent economic centers. Scottsdale has its own financial district. Tempe is home to Arizona State University and one of the strongest job corridors in the Southwest. Mesa, the third-largest city in Arizona, has attracted aviation and manufacturing employers that have little to do with Phoenix proper.
This scale matters for co-buyers because it means genuine choice. Unlike San Francisco, where affordability pressure has compressed everyone into a narrow set of viable neighborhoods, Phoenix offers a wide band of options at different price points and lifestyle profiles. Two buyers who want walkability and nightlife can focus on Tempe or central Phoenix. A group prioritizing space and newer construction can look at Queen Creek, Surprise, or Peoria. People who want access to hiking and outdoor recreation without giving up proximity to employers can find that in multiple parts of the metro.
The Valley's job market is also genuinely diverse. TSMC's $65 billion semiconductor campus in north Phoenix, Intel's longstanding Chandler facilities, Amazon and Apple distribution and corporate operations, a growing healthcare sector, and the continued expansion of financial services firms relocating from higher-cost states have all deepened the employment base. That diversity matters for co-buyers because it increases the likelihood that two or three people with different employers can all find work close to a single home.
Arizona Community Property Law: What Co-Buyers Need to Know
Arizona is one of nine community property states in the United States. This is relevant for co-buyers primarily because it shapes how existing marital property interacts with co-ownership arrangements.
If one of your co-buyers is married, their spouse may have a community property interest in assets acquired during the marriage, which can affect financing, title, and what happens to their share if they divorce. Lenders often require the non-borrowing spouse to sign a quit-claim deed or consent to the transaction even when they are not on the loan. This is standard procedure in Arizona and is not a barrier to co-buying, but it is something every co-buyer group needs to address explicitly before closing.
Co-ownership through an ownership entity, which is how Rhome structures co-owned homes, provides a clear organizational layer. Each member's ownership interest is their asset. The governance agreement governs what happens to that interest under various scenarios, including death, disability, divorce, or a member wanting to exit. Working with an Arizona real estate attorney to draft or review the co-ownership agreement is worth every dollar spent.
The good news: Arizona has no state income tax on long-term capital gains for most primary residence sales (subject to the federal exclusion limits), and property taxes in the Valley are generally lower than comparable markets in California, Texas, or the Northeast.
Key Areas Across the Valley
Scottsdale
Scottsdale operates at the premium end of the Phoenix market. Median home prices in Scottsdale proper range from $650,000 in southern and central areas to well over $1 million in north Scottsdale communities like DC Ranch, Silverleaf, and Troon. The draw is real: exceptional dining, proximity to McDowell Sonoran Preserve and hundreds of miles of trail access, a strong arts and culture scene, and a job market anchored by financial services, healthcare, and technology firms.
For co-buyers, Scottsdale is the market where splitting costs makes the most immediate financial sense. Two buyers contributing to a $700,000 purchase are each managing a situation that would otherwise require close to a quarter million dollars in income to sustain alone. Co-ownership brings Scottsdale within range for two working professionals who would each be priced out independently.
Tempe and Mesa
Tempe and Mesa are where much of the practical co-buying action is in the Phoenix metro. Median prices in Tempe hover around $450,000 to $500,000, while Mesa's broader range offers genuine entry points in the $350,000 to $450,000 range depending on proximity to major employment corridors.
Tempe's light rail connectivity, ASU's economic influence, and the concentration of tech employers along the 101 and 202 corridors make it a natural fit for co-buyers in their late twenties and thirties who want urban amenities without downtown Phoenix prices. Mesa's sheer size means enormous variety, from historic districts near downtown Mesa to newer master-planned communities in east Mesa near the Superstition Mountains.
Glendale and Peoria
Glendale and Peoria represent the northwest Valley's answer to affordability, and both have matured into genuine cities with real infrastructure. State Farm Stadium, Gila River Arena, and the surrounding entertainment district have given Glendale an identity beyond its residential roots. Median prices in Glendale generally range from $340,000 to $400,000, and newer construction in Peoria and neighboring Surprise can be found for similar figures.
For co-buyers who prioritize space, newer builds, and lower price per square foot, the northwest Valley is compelling. A group of two buyers could purchase a 2,400-square-foot home in Peoria for what a studio apartment costs in West Los Angeles. That is not a hypothetical. It is the arithmetic of Sun Belt geography.
Surprise and the West Valley
Surprise has been one of the fastest-growing cities in the entire country for multiple years running. Its population has more than doubled in the past fifteen years, and it continues to attract buyers priced out of closer-in communities. New construction is prevalent, HOA amenities are often included in master-planned communities, and the commute to employers in the northwest Valley and along the Loop 303 corridor is manageable.
For a co-buyer group that includes someone with a longer time horizon or who values newer construction, Surprise and neighboring El Mirage and Avondale offer the kind of value that feels increasingly rare in Sun Belt metros.
Arizona Department of Housing Programs
The Arizona Department of Housing administers several programs relevant to first-time buyers, including co-buyers in some configurations. The HOME Plus program provides down payment assistance paired with a 30-year fixed-rate mortgage through participating lenders. The assistance comes in the form of a grant or a second mortgage depending on the program variant.
Income limits, purchase price caps, and lender participation requirements apply, and these programs are designed primarily for individual borrowers rather than entity structures. Co-buyers using the Rhome model should speak with a Rhome-affiliated lender early in the process to understand which assistance programs are compatible with their co-purchase structure. The landscape changes as programs are renewed or modified, and a current conversation with a lender beats any static resource.
Maricopa County also occasionally runs its own assistance programs, and some municipalities including Mesa and Tempe have offered homebuyer assistance at the city level. These are worth asking about, though availability fluctuates with funding cycles.
FHA Co-Buying Math in the Valley
FHA loans allow a down payment as low as 3.5% of the purchase price for buyers with credit scores of 580 or above. On a $400,000 Phoenix-area home, that means a total down payment of $14,000. Shared across two buyers, that is $7,000 each. Shared across three, it is just over $4,600 each.
That is not a typo. Three buyers co-purchasing a $400,000 home under an FHA structure each need to bring roughly $4,600 to close, plus their share of closing costs.
For comparison, a solo buyer targeting the same $400,000 home with a conventional 20% down payment needs $80,000 upfront before closing costs. FHA brings that to $14,000, but even that figure can be a multi-year savings project for someone earning $55,000 to $75,000 per year in a Valley with a real cost of living.
The FHA co-buying math also changes the debt-to-income picture. Monthly principal, interest, taxes, and insurance on a $400,000 home at current rates runs roughly $2,600 to $2,900 per month depending on rate, taxes, and insurance. Divided three ways, each co-buyer's housing cost drops to under $1,000 per month. That is a number most working adults in Phoenix can sustain even during periods of job transition or reduced income.
Mortgage insurance is part of the FHA picture: an upfront premium of 1.75% of the loan amount plus an annual premium that runs about 0.55% to 0.85% depending on loan terms. This is a real cost, and co-buyers should factor it in. But for most groups who lack a substantial down payment, FHA's structure still produces a lower monthly payment than a conventional loan at a higher down payment, because the total loan amount is lower when the down payment is pooled.
Why Co-Ownership Fits Phoenix's Affordability Math
Phoenix has a specific affordability problem that is different from, say, San Francisco's. In the Bay Area, home prices have risen so far beyond local income levels that even well-paid workers struggle. Phoenix prices are high relative to local wages, but they are not astronomically detached. The gap is real and painful, but it is bridgeable with the right structure.
The median household income in the Phoenix metro is approximately $65,000 to $70,000. At that income level, conventional affordability guidelines suggest a home price of roughly $250,000 to $280,000. Median home prices in the Valley are nearly double that. The gap is about $140,000 to $160,000 on a median basis, which is significant but not infinite.
Co-ownership closes that gap directly. Two buyers with household incomes of $65,000 each have a combined qualifying income of $130,000. At $130,000, the conventional affordability guideline suggests a purchase price around $500,000 to $520,000, which covers much of the Valley. Three buyers at that income level can reach into Scottsdale.
Beyond the math, Phoenix is a city where people are building lives, not just biding time. The buyers who are most drawn to co-ownership in the Valley are people who want to own, who are tired of renting, who recognize that equity accumulation is real and that waiting for perfect solo conditions might mean waiting a very long time. Co-ownership is not a compromise for them. It is a strategy.
How Rhome Works in Phoenix
Rhome structures co-owned homes through an ownership entity, with each buyer holding an ownership interest proportional to their contribution. The governance agreement defines how the group makes decisions, how costs are split, what happens if someone wants to leave, and how eventual sale proceeds are distributed.
All co-buyers must occupy the home as their primary residence. This is a foundational requirement, not a preference. The FHA loan structure, the tax treatment, and the entire Rhome model depend on every member living in the home. This distinguishes Rhome from investment or rental scenarios. You are buying a home to live in, with co-owners who are also living there.
Rhome works with a network of lenders experienced in co-purchase transactions and real estate attorneys familiar with Arizona LLC formation and property law. The platform handles the coordination layer: matching compatible co-buyers, structuring the agreement, and supporting the group through closing and beyond.
For Phoenix buyers specifically, Rhome is seeing interest from two main groups. The first is friend pairs or groups, often in their late twenties and early thirties, who have been renting together and want to convert that arrangement into equity-building ownership. The second is people who know they want to own in a specific part of the Valley but cannot qualify solo and are open to finding compatible co-buyers through Rhome's matching process.
Both paths work. The starting point is the same: a conversation about what you can contribute, where you want to live, and what you need from a co-ownership agreement.
FAQ
See faqItems.