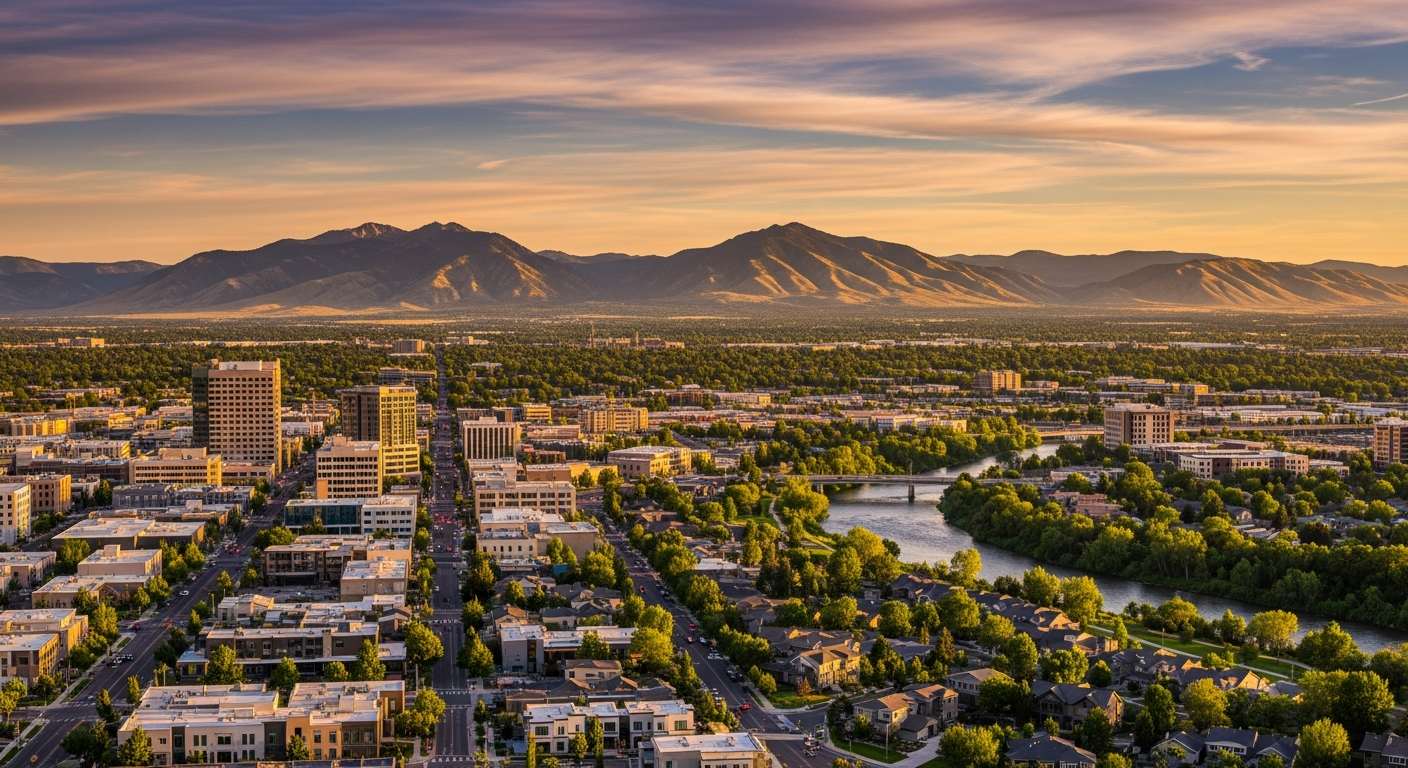
Boise spent decades as a well-kept secret. Outdoorsy, affordable, and close enough to the mountains that you could leave the office on a Friday afternoon and be skiing by dinner. Then the pandemic happened, remote work normalized, and somewhere between 2020 and 2022, a significant share of California, Washington, and Oregon decided that the secret was too good not to share.
The result was a housing market that moved faster than most buyers were prepared for. Prices climbed sharply. Inventory dried up. And the classic path to homeownership, saving alone and buying alone, started to feel less realistic for a lot of people who genuinely wanted to put down roots in Idaho.
Co-ownership changes the math. Two to four people buy a primary residence together through a structured ownership entity, each living in the home as their primary home, each building equity as the market moves. This guide covers how that works in Idaho specifically, including the legal framework, the Boise market context, neighborhood options, available assistance programs, and how Rhome structures the whole thing.
Idaho Real Estate Law and the Ownership Entity Framework
Idaho is a community property state, but that designation applies only to legally married couples. For everyone else, including co-buyers who are friends, family members, or colleagues, Idaho follows common law property principles. That means each co-owner's interest in a property is determined by how title is held, not by any presumption of shared ownership.
This is exactly why co-buying through an ownership entity makes so much sense in Idaho. When two or three buyers form a co-ownership entity and take title in its name, the ownership percentages, decision rights, and exit procedures are all spelled out in a governance agreement rather than left to chance. Each member owns a defined share of the entity, the entity owns the property, and the governance agreement covers everything from how expenses are split to what happens if one person wants to sell their share.
Idaho has a relatively straightforward process for forming a co-ownership entity. The state charges a modest formation fee, annual report requirements are simple, and the legal infrastructure for single-asset residential entities is well-established. There is no state income tax in Idaho, which matters for how rental income or sale proceeds flow through the structure. Any gains or losses pass through to members individually, and Idaho does not impose an additional layer of entity-level taxation.
One thing to understand clearly: Rhome co-ownership is not an investment structure. All members must occupy the home as their primary residence. Idaho law and Rhome's model both require genuine occupancy, and the FHA financing that powers most Rhome purchases requires it as a condition of the loan. This is a home you live in, not an asset you hold passively.
For community property purposes, if a married couple participates in a Rhome co-ownership alongside other buyers, their share of the entity is treated as community property between them. That does not affect how the entity or the co-ownership agreement functions, but it is worth knowing if estate planning is a consideration.
What Drove Boise's Growth
To understand why co-ownership makes sense in Boise right now, it helps to understand what happened to the market over the past five years.
Boise had always grown steadily. The presence of Micron Technology, HP's Boise campus, and a growing tech sector gave the city a stable employment base. Boise State University anchored the downtown corridor and kept younger residents cycling through the area. But the city's growth was measured, not explosive.
That changed in 2020 and 2021. Remote work eliminated the geographic constraint that had kept many high earners tethered to coastal metros. Boise, with its relative affordability, quality outdoor access, low crime, and strong school districts, became an extremely attractive destination for workers from the Bay Area, Seattle, Portland, and beyond. New residents arrived in significant numbers, and they arrived with significant purchasing power relative to local incomes.
Home prices reflected the demand. Median values in the Boise metro climbed dramatically between 2020 and 2022. Some neighborhoods that had been comfortably attainable for median-income buyers moved out of reach almost overnight. By the time the market began to cool in late 2022 and into 2023 as rates rose nationally, prices had reset to a new baseline that was substantially higher than pre-pandemic levels.
For buyers entering the market today, that new baseline is the reality. Boise is no longer as cheap as it once was relative to coastal markets, but it remains more affordable than Seattle or San Francisco, and it continues to attract remote workers, relocating families, and tech employees from established Idaho employers. The long-term demand picture for the market is strong.
That context is precisely what makes co-ownership an interesting option. When a market has already run up and offers strong long-term fundamentals, buying into it sooner with a co-buyer is often better than waiting to accumulate a full down payment alone while prices continue moving.
Key Neighborhoods Worth Knowing
Boise and the surrounding communities offer a range of neighborhoods with distinct character and price points. Co-buyers tend to gravitate toward areas with strong walkability, good access to downtown, or specific lifestyle features that match what the group is looking for.
The North End is Boise's most established residential neighborhood. Tree-lined streets, Craftsman bungalows, and proximity to Hyde Park's shops and restaurants make it one of the most sought-after addresses in the city. The North End sits at a premium, and entry prices there reflect it. For a co-buying group, it becomes accessible in a way that it simply would not be for a solo buyer at the same income level.
The East End runs along the foothills and offers a mix of older homes and newer construction, with strong access to the Boise Greenbelt and foothills trail system. Buyers who prioritize outdoor access without sacrificing proximity to downtown tend to land here.
Downtown Boise itself has seen significant infill development, with condos and townhomes within walking distance of the Capitol building, Treefort Music Hall, and a restaurant scene that has grown considerably in the past decade. Downtown works well for co-buyers who want urban convenience and are open to smaller square footage in exchange for location.
Meridian is the fastest-growing city in Idaho by some measures and sits just west of Boise. It offers newer construction, larger lots, and lower price points than comparable properties closer to downtown. Families and buyers who want more space often find that Meridian delivers the most square footage per dollar in the metro.
Eagle is a smaller, quieter community northwest of Boise that has attracted significant growth from families seeking a suburban feel with easy freeway access to Boise's employment centers. Eagle's home values have risen sharply alongside the broader metro, but it remains an option for co-buying groups looking for more space and newer inventory.
IHFA Programs for Idaho Homebuyers
The Idaho Housing and Finance Association offers several programs that can layer into a Rhome co-buying structure, depending on the income and eligibility of the buyers involved.
The First Loan program provides a competitive 30-year fixed-rate mortgage, often with rates below market. It is income-limited and has purchase price caps that vary by county, but in Ada County (where Boise sits), the limits are calibrated to reflect local market conditions.
The Second Loan program pairs with the First Loan to provide down payment and closing cost assistance. Eligible buyers can receive a second loan of up to a fixed percentage of the purchase price, structured at a low interest rate with a repayment schedule tied to the first mortgage. For co-buyers who are each contributing to the down payment, this kind of assistance can meaningfully reduce the out-of-pocket requirement at closing.
The Mortgage Credit Certificate (MCC) is a federal tax credit available through IHFA that allows eligible first-time homebuyers to claim a credit on a portion of the mortgage interest they pay each year. Unlike a deduction, this is a dollar-for-dollar reduction in tax liability. For co-buyers who each qualify as first-time buyers, each member of the group may be able to access the MCC benefit on their individual tax return, depending on how the entity allocates interest expense among members. Tax treatment varies by situation, so individual advice from a CPA is important here.
IHFA eligibility generally requires that buyers meet income limits and meet the definition of a first-time homebuyer, defined as someone who has not owned a primary residence in the past three years. Not every co-buyer in a Rhome group needs to be a first-time buyer, but those who are may be able to take advantage of these programs for their portion of the financing.
The FHA Co-Buying Math in Boise
Most Rhome purchases use FHA financing, which requires a minimum 3.5% down payment on the total purchase price. The key distinction in a co-ownership structure is that this down payment is split among the buyers, so each person's individual contribution is a fraction of the total.
To make the math concrete without inventing specific numbers: if two buyers purchase a home together in Boise, each person's down payment contribution is half of the 3.5% total. For a $450,000 home, the total down payment is $15,750. Each buyer contributes $7,875. That is a very different proposition than trying to save $15,750 alone, especially in a market where prices moved up significantly in recent years.
Add two more buyers and the individual contribution drops further. For a three-person group on the same home, each person contributes approximately $5,250 toward the down payment. For a four-person group, it is under $4,000 per person.
Monthly mortgage payments follow the same logic. The principal, interest, taxes, and insurance that a solo buyer would carry alone get divided among the co-owners according to ownership percentage. For buyers in Boise who might otherwise be priced out of the neighborhoods they actually want to live in, that division can be the difference between renting indefinitely and owning equity in a home that appreciates with the market.
Why High-Growth Markets Favor Co-Ownership's Timing
There is a particular version of the co-ownership argument that applies specifically to markets like Boise: the equity timing argument.
In a market that has already seen significant appreciation and continues to attract sustained demand, the cost of waiting is real. Every year a buyer spends saving toward a full individual down payment is a year of potential equity growth that someone else captures. If prices rise 4% annually on a $450,000 home, that is $18,000 in appreciation in year one alone. A buyer who waits two years to save enough to buy alone has effectively paid $36,000 or more in opportunity cost, while also paying rent throughout that period.
Co-ownership lets buyers enter the market sooner at a lower individual barrier. The home appreciates regardless of how many people own it. When the time comes to sell or one co-owner buys out another, all members benefit from whatever equity has accumulated over the ownership period.
This is not a guarantee. Real estate markets can and do soften, and any buyer should go in understanding that. But for a market with Boise's employment base, migration patterns, and continued infrastructure investment, the long-term demand argument is solid. Getting in sooner, even with a partner, often beats waiting longer to go it alone.
How Rhome Works in Idaho
Rhome structures the entire co-ownership process, from finding compatible co-buyers to setting up the ownership entity to coordinating the FHA purchase. Here is how the process looks for a Boise buyer.
You start by browsing homes and indicating your preferences. Rhome matches you with co-buyers who have compatible housing goals, budget ranges, and lifestyle priorities. Before any purchase moves forward, the group goes through a compatibility process to make sure everyone is aligned on expectations.
Once a group is formed, Rhome handles the legal structure. An Idaho ownership entity is formed, and a co-ownership agreement is drafted that covers ownership percentages, monthly payment responsibilities, maintenance protocols, and what happens if one person wants to exit. This agreement is the foundation that makes the whole arrangement work cleanly over time.
Financing flows through Rhome's structure using an FHA-backed loan, with each co-buyer's individual creditworthiness and income factoring into qualification. Rhome works with lenders who are experienced with this structure, so the process does not require each buyer to separately navigate an unusual loan type.
After closing, Rhome's platform helps the group manage the ongoing shared responsibilities: tracking payments, coordinating maintenance decisions, and providing a clear process if and when a co-owner wants to sell their share or the group decides to sell the whole property.
For Idaho buyers, the process is the same as in any Rhome market. The entity is formed under Idaho state law, the purchase is recorded with Ada County (or the relevant county assessor), and all parties occupy the home as their primary residence from day one.
Frequently Asked Questions
See the FAQ section below for answers to common questions about co-ownership in Idaho.