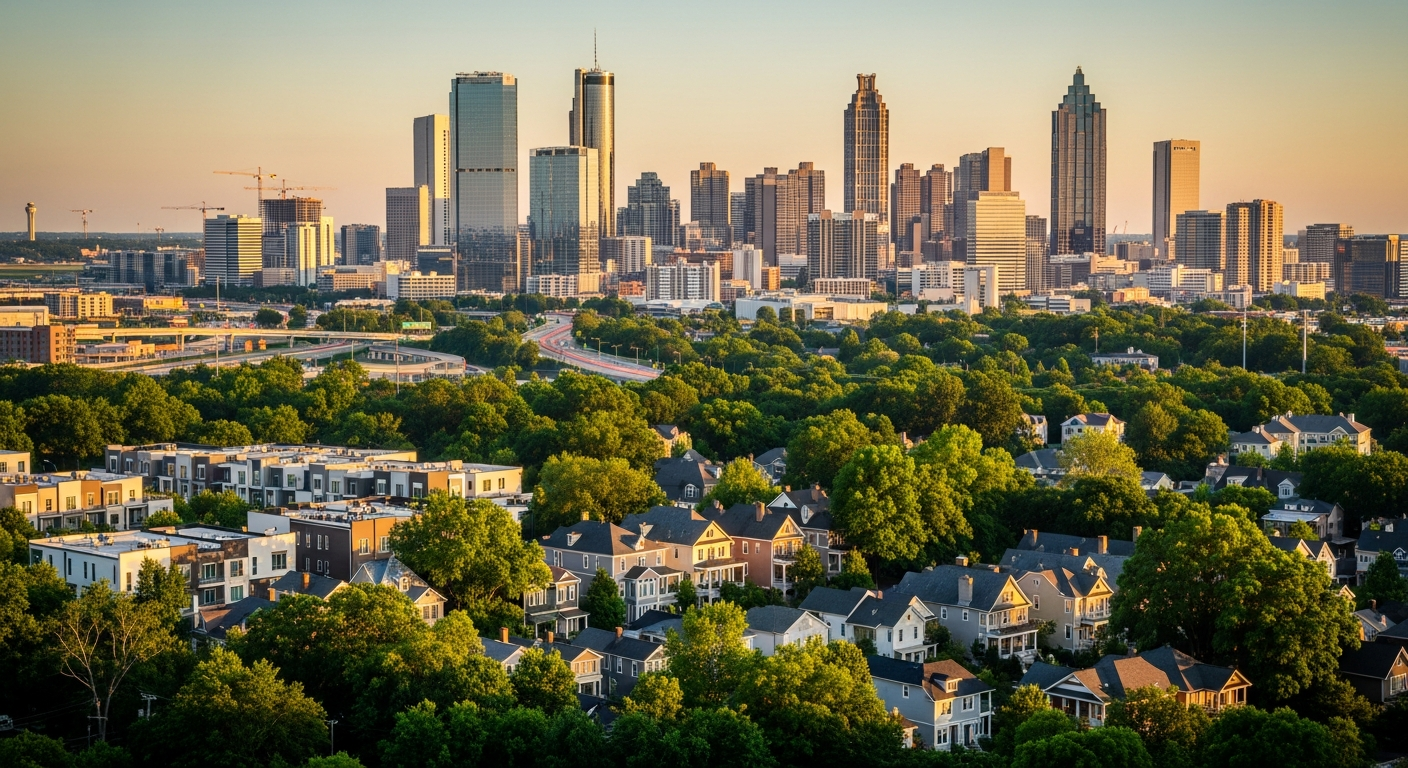
Atlanta is one of the few American cities that has managed to keep growing at a pace that genuinely surprises people who left a few years ago. The metro area has added hundreds of thousands of residents over the past decade, anchored by a corporate headquarters economy that keeps pulling in young professionals from across the country. Delta, Home Depot, Coca-Cola, NCR Voyix, Cox Enterprises, and a growing constellation of tech firms have made the city a legitimate economic anchor for the entire Southeast.
That growth is the context for understanding why Atlanta's housing market is what it is today, and why co-ownership has become a genuinely smart path for a specific kind of buyer here.
Why Atlanta Is the South's Housing Anchor
Atlanta functions differently from other major Southern cities because of how its economy is structured. Nashville has hospitality and healthcare. Charlotte has banking. Houston has energy. Atlanta has all of it: logistics, film and television production, cybersecurity, retail headquarters, and an international airport that makes the city a global connector.
The result is consistent, broad-based demand for housing. When one sector softens, others pick up the slack. That diversification has kept Atlanta's housing market relatively stable even through national corrections, and it has supported steady long-run appreciation that makes ownership meaningful over time.
The city also draws a particular demographic mix worth understanding if you are thinking about co-buying. Atlanta has one of the largest concentrations of Black college graduates in the country, a large LGBTQ+ community concentrated in neighborhoods like Old Fourth Ward and Midtown, and a fast-growing immigrant population in areas like Chamblee and Duluth. The result is a city where the social fabric genuinely supports non-traditional household formation. Co-buying with a friend, sibling, or partner who is not a spouse fits naturally into how many Atlantans already live.
What Georgia Law Means for Co-Buyers
Before getting into neighborhoods and numbers, it helps to understand the basic legal environment. Georgia is a relatively straightforward state for real estate co-ownership. The state recognizes LLCs as valid holding structures for residential property, which is central to how Rhome structures its co-ownership arrangements.
Holding a home through an LLC gives co-buyers a formal legal framework for the most important questions: who owns what share, what happens if one person wants to sell, how decisions get made about the property, and how costs get split. Without that structure, disputes between co-owners default to Georgia's general property law, which tends toward partition actions that force a sale, often at a bad time.
Georgia does not have any specific co-ownership statutes the way some states do, but the LLC path is well-established and understood by Georgia real estate attorneys. If you are working with Rhome, the co-ownership agreement and ownership structure are set up for you. If you are going it alone, budget for a real estate attorney and make sure your governance agreement covers the scenarios that matter.
Key Neighborhoods for Co-Buyers in Atlanta
Atlanta's geography is unusually fragmented. The city proper sits inside a ring of independent municipalities, and what most people think of as "Atlanta" includes places like Decatur, Sandy Springs, and Smyrna that have their own governments, school systems, and character. This matters for co-buyers because the right neighborhood depends on what you and your co-buyer prioritize.
Intown Atlanta: Virginia Highland
Virginia Highland is one of the most consistently desirable Intown neighborhoods, and it represents the classic Atlanta challenge: you want to live there, but the entry price is real. Craftsman bungalows and renovated four-squares sit on quiet streets within walking distance of restaurants and coffee shops on Highland Avenue. Homes in Virginia Highland regularly list above $600,000, and well-maintained properties move quickly.
For two buyers splitting a purchase at that price point, the math starts to work. An FHA loan at 3.5% down on a $620,000 home requires roughly $21,700 total, which divides to around $10,850 per buyer. Monthly carrying costs become manageable in a way they simply are not for a single buyer at the same income. Virginia Highland rewards co-buyers who want walkability and long-term neighborhood stability.
Intown Atlanta: East Atlanta Village
East Atlanta Village has a more eclectic character, with a music venue scene, independent restaurants, and a housing stock that ranges from small shotgun houses to larger four-bedroom homes that can accommodate two households comfortably. Prices are generally more accessible than Virginia Highland, which makes East Atlanta an attractive entry point for first-time co-buyers.
The neighborhood has appreciated meaningfully over the past decade and still has room to run compared to the most polished Intown areas. For co-buyers looking to maximize long-term equity growth from a lower starting price, East Atlanta deserves a close look.
Suburban Options: Decatur
Decatur is technically its own city, completely surrounded by Atlanta, and it operates with an independent identity that its residents take seriously. Excellent public schools, a walkable downtown with restaurants and a farmers market, and a housing stock that includes both small cottages and larger family homes make Decatur one of the most desirable addresses in the metro.
Decatur prices have risen sharply over the past several years, which actually strengthens the co-buying case. Entry-level single-family homes in Decatur require meaningful down payments and carry significant monthly costs. Two co-buyers splitting those costs can access a Decatur address that would be a stretch for either of them individually.
Suburban Options: Smyrna
Smyrna sits northwest of Atlanta, close to the Battery Atlanta complex and Truist Park, and it has transformed significantly over the past decade. New mixed-use development, improved transit connections, and a growing restaurant scene have made Smyrna attractive to buyers who want more space than Intown Atlanta offers at a more accessible price.
For co-buyers prioritizing square footage, Smyrna is worth serious consideration. Four-bedroom homes exist here at prices that would get you a small two-bedroom in Virginia Highland, and the neighborhood trajectory has been consistently positive.
Suburban Options: Sandy Springs
Sandy Springs is the upscale northern alternative, with a well-established commercial district, proximity to major employers, and a housing stock that skews toward larger single-family homes and townhouses. It appeals to co-buyers who want suburban space without sacrificing access to the northern employment corridors along GA-400.
Prices in Sandy Springs are higher than Smyrna but the neighborhood offers strong schools, low crime, and the kind of stability that makes long-term ownership feel predictable.
The Georgia Dream Program
Georgia has a state-sponsored down payment assistance program called Georgia Dream, administered by the Georgia Department of Community Affairs. The program offers low-interest first mortgage loans and down payment assistance grants to qualifying buyers, with income limits and purchase price caps that vary by county.
The standard Georgia Dream down payment assistance provides help toward down payment and closing costs, and there are enhanced programs for certain public service workers, active duty military, and buyers with disabilities. Income limits are set by county and household size, so buyers in different parts of the metro face different eligibility thresholds.
For co-buyers specifically, it is worth checking eligibility carefully. Each buyer's income counts toward the household income limit, which may affect qualification depending on what each person earns. A Rhome advisor can help you think through how Georgia Dream interacts with an FHA co-purchase before you commit to a path.
The FHA Co-Buying Math in Atlanta
The Rhome model uses FHA financing, which allows a 3.5% total down payment. That down payment is shared across all co-buyers, which is the core financial logic that makes co-ownership work as an affordability strategy.
Consider a home in East Atlanta Village listed at $420,000. A conventional loan at 20% down would require $84,000 before closing costs, a sum that stops many buyers cold. An FHA loan at 3.5% down requires $14,700 total. Split between two buyers, that is $7,350 each, plus a share of closing costs.
On a $600,000 home in Virginia Highland, the FHA down payment is $21,000 total, or $10,500 per buyer. Monthly principal and interest at a 7% rate on a $579,000 loan runs roughly $3,852. Split two ways, each buyer's share is around $1,926 before taxes, insurance, and HOA fees where applicable.
These numbers are illustrations, not guarantees. Actual rates, loan amounts, and costs depend on credit scores, current market conditions, and the specific property. But the structure reveals why co-ownership in a market like Atlanta is not just an affordability hack: it is a way to access neighborhoods that appreciate meaningfully over time, with a down payment and monthly payment that reflects current income rather than a decade of savings.
All co-buyers must intend to occupy the home as a primary residence. This is a firm requirement for FHA financing and a core principle of the Rhome model. The home you co-own through Rhome is your home, not a rental and not an investment vehicle.
Why Atlanta's Price Trajectory Makes Co-Buying Timely
Atlanta's long-run price appreciation has been strong, but it has not followed the straight-up trajectory of coastal markets like Seattle or San Diego. There have been periods of slower growth and even modest softening, which can make the city feel less urgent to would-be buyers who are waiting for a "better" moment.
The case for acting now rather than waiting is not about predicting a price spike. It is about two things that are more reliable than market timing. First, Atlanta has a structural supply problem: the city's growth has consistently outpaced new construction in the most desirable Intown and close-in suburban neighborhoods, and that mismatch tends to support prices over time. Second, every year of renting is a year of building someone else's equity rather than your own.
For two buyers who are currently renting in Atlanta, the calculus is worth doing carefully. If you can co-buy a home in a neighborhood you want to live in, with a payment that is competitive with or lower than your combined rent, and you are building equity in a market with a solid long-run track record, waiting carries its own cost.
How Rhome Works in Atlanta
Rhome provides the structure that makes co-ownership work as a clean, legally sound arrangement rather than an informal agreement between friends who hope it goes well.
The process starts with finding co-buyers who are ready to buy together, typically two to four people who share a vision for where they want to live and how they want to own. Rhome sets up the ownership entity that holds the property, drafts the co-ownership agreement that covers all the key scenarios, and coordinates the FHA financing process so all co-buyers are properly on the loan.
Once you are in the home, Rhome provides an ongoing platform for managing the shared ownership: tracking each co-owner's equity stake, handling communication between co-owners, and providing a structured process for the eventual exit when one or more owners is ready to sell their share or move on.
In Atlanta specifically, Rhome works with buyers across the metro, from Intown neighborhoods to the close-in suburbs. If you already have a co-buyer in mind, or if you are exploring whether the model could work for your situation, the starting point is a conversation about the neighborhoods you are drawn to and what you can realistically put together as a down payment.
Atlanta is a city that rewards people who get into the market. Co-ownership is a way to do that earlier, in a better neighborhood, with a financial structure that is built to last.
Frequently Asked Questions
See below.