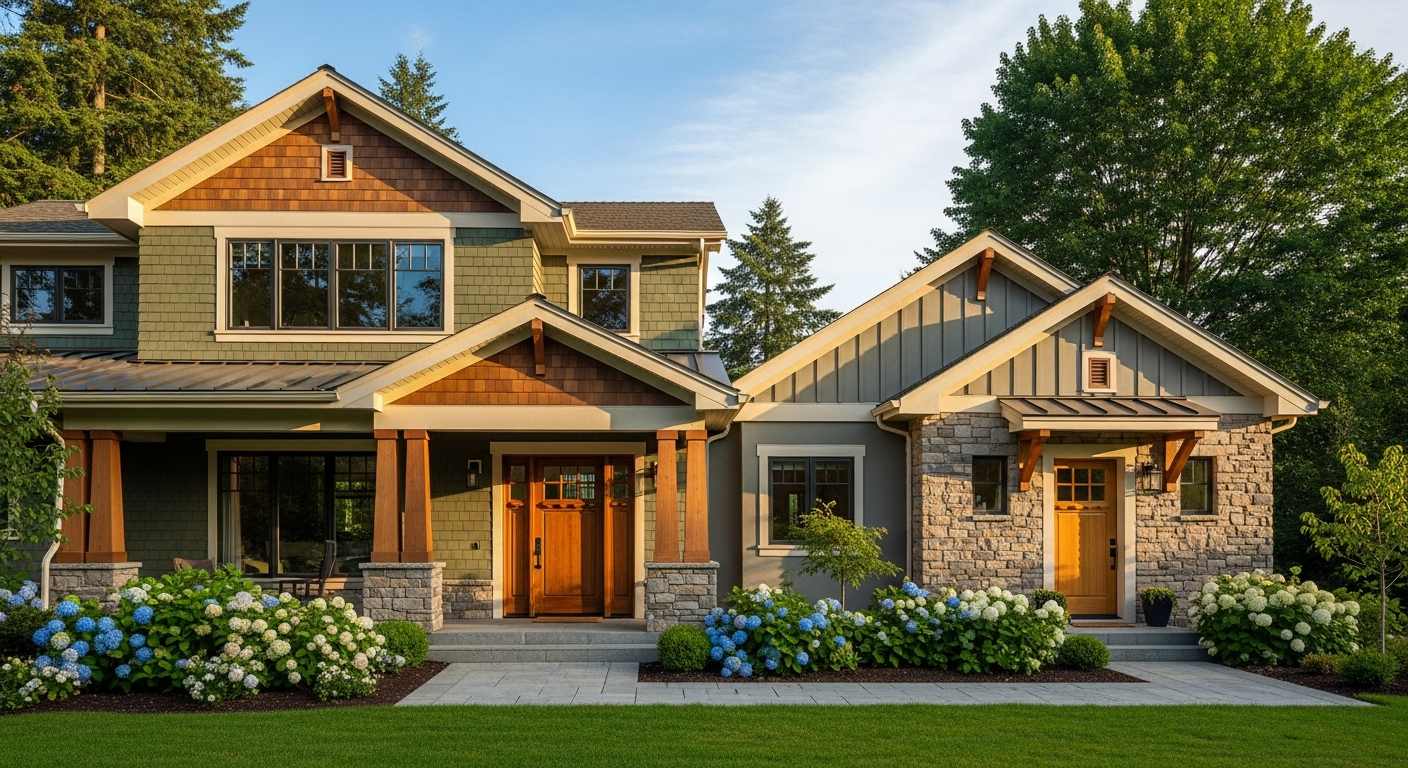
A home with an in-law suite sounds like an ideal co-buying setup. Two households, two front doors, one shared mortgage. In practice, properties with a second unit are among the most naturally suited to co-ownership, and they come up often when co-buying groups start their property search.
But they also come with rules that are easy to misunderstand. Before you fall in love with a floor plan, it is worth knowing exactly how these properties work under Rhome's co-ownership model.
Why In-Law Suites Work So Well for Co-Buyers
The appeal is straightforward: more private space per co-owner.
In a standard co-owned home, co-owners typically divide up bedrooms and share common areas. That works well for many groups, especially close friends or siblings who are comfortable sharing a kitchen and living room. But for co-owners who want a higher degree of independence, a home with a second unit changes the equation entirely.
An in-law suite or attached accessory dwelling unit (ADU) typically includes its own sleeping area, bathroom, and sometimes a small kitchen or kitchenette. One co-owner or co-owner household uses the primary residence. The other uses the suite. Both are living in the same property, sharing the costs and the mortgage, but each with their own front door and their own daily rhythm.
For co-buyers who are close but still want to keep their households separate, this structure offers a kind of built-in privacy that a standard three-bedroom rarely can.
The Rule You Need to Know First
Here is where many people get tripped up, and it is important to be completely clear about this before anything else.
Under Rhome's co-ownership model, the in-law suite or second unit cannot be rented out. Not to a third party, not on a short-term basis, not at all.
All co-owners in a Rhome co-ownership must use the property as their primary residence. This is not a technicality in fine print. It is a foundational requirement of the model.
When people hear "home with a second unit," many immediately think about the rental income that second unit could generate. That line of thinking is understandable, but it is not compatible with Rhome. Subleasing any portion of the property is prohibited. The second unit, like the rest of the home, must be used by a co-owner as their primary residence.
This means the two most common arrangements for a co-owned home with a second unit are:
- Two individual co-owners, where one occupies the main house and the other occupies the suite, and both treat the property as their primary residence.
- Two co-owner households, with a similar split, where each household lives in their respective unit full time.
If your plan is to buy a two-unit property and have one co-owner live in it while you collect rent on the other side, that is not what Rhome is built for. Rhome is a homeownership platform, not a rental investment vehicle.
How the In-Law Suite Affects the Ownership Split
When co-owners occupy meaningfully different amounts of space, equal ownership percentages often do not feel fair. This is a common conversation, and it has a practical answer.
Ownership percentages in a Rhome co-ownership do not have to be equal. They are negotiated between co-owners and structured into the co-ownership agreement. If one co-owner is getting a 900-square-foot main house and the other is getting a 400-square-foot suite, it is reasonable for the ownership split to reflect that difference.
The typical approach is to weight the split based on a combination of factors:
Relative square footage. This is the most direct measure. If the primary unit is twice the size of the suite, that could translate into a proportionally larger ownership share for the co-owner occupying it.
Down payment contribution. Co-owners often contribute different amounts to the down payment, and that affects their starting ownership percentages as well.
Amenity access. Does the in-law suite have its own outdoor space? Its own parking spot? Does the main house have a garage that the suite does not access? These details matter when negotiating a fair split.
Shared costs. Regardless of the ownership split, co-owners will share mortgage payments, property taxes, and maintenance costs in proportion to their ownership percentages. The agreement should spell out exactly how shared expenses in common areas are handled.
There is no formula that works for every situation, but the goal is the same: each co-owner should feel that their ownership percentage fairly reflects what they are getting. Rhome's co-ownership agreement is structured to accommodate these kinds of space-based differences, and working through it carefully at the outset prevents friction later.
How In-Law Suites Affect FHA Financing
Many co-buyers use FHA loans, and properties with in-law suites or ADUs have specific rules under FHA guidelines worth understanding before you make an offer.
The FHA defines an accessory dwelling unit (ADU) as a habitable living unit that includes sleeping, cooking, and bathroom facilities, and is subordinate in size to the primary dwelling on the same lot. An in-law suite typically qualifies as an ADU under this definition if it has its own kitchen or kitchenette.
For FHA appraisal purposes, a few things happen differently when a property has an ADU:
The appraiser evaluates it as part of the whole. FHA appraisers are trained to identify ADUs and assess whether the unit adds value to the property. The presence of a legal, permitted ADU generally supports a higher appraised value, which can benefit buyers.
The ADU must be legal and permitted. FHA lenders will want to confirm that the second unit is a lawfully permitted structure, not a converted garage done without permits. Unpermitted units can create appraisal issues and may affect loan eligibility. Always verify permit status before making an offer on a property with a second unit.
Rental income from an ADU is sometimes counted for qualification purposes, but Rhome's model does not use that unit as a rental. FHA guidelines do allow lenders to count projected rental income from an ADU toward borrower qualification in certain situations. That rule exists for owner-occupants who plan to rent the secondary unit. Since Rhome co-owners cannot rent the unit, this particular qualifying factor is not in play. Your qualification is based on your actual income and the income of your co-owners, not on projected rent.
Properties with separate utilities may be classified differently. Some two-unit properties are classified as duplexes rather than single-family homes with ADUs. The distinction matters for FHA loans, which have separate loan limits and down payment considerations for two-unit properties versus single-family homes. Make sure you and your lender understand how the property is classified before you proceed.
If you are financing a co-ownership purchase with an FHA loan, working with a lender who has experience with multi-unit owner-occupied properties will save you a lot of confusion.
Questions About Space-Based Ownership Splits
When co-buyers start thinking through how to divide ownership on a property with a second unit, a few questions come up consistently.
Does one co-owner have to pay more of the mortgage because they have more space?
Not necessarily in dollar terms that are separate from ownership percentage. Mortgage payments are typically split in proportion to ownership. If one co-owner owns 60% and the other owns 40%, they pay 60% and 40% of the monthly mortgage, respectively. The ownership percentage already accounts for the space difference, so there is no separate "space surcharge." The goal is to set an ownership split at the outset that both parties feel reflects the value they are each receiving.
What if the in-law suite owner wants to eventually move into the main house?
This is a question about what happens if co-owners want to change their living arrangements. The short answer is that it requires the consent of both co-owners and a revision to the co-ownership agreement. Co-ownership agreements should address how space allocation can change over time and under what conditions.
What if the suite is unfinished or we plan to build one out after purchase?
This is a renovation and financing question more than a co-ownership structure question. If the suite does not yet exist, it cannot factor into the appraisal or the initial ownership split. You would be buying the property as-is and planning future improvements. Renovation financing options exist, but they add complexity. It is generally cleaner to co-buy a property where the second unit already exists and is legally permitted.

