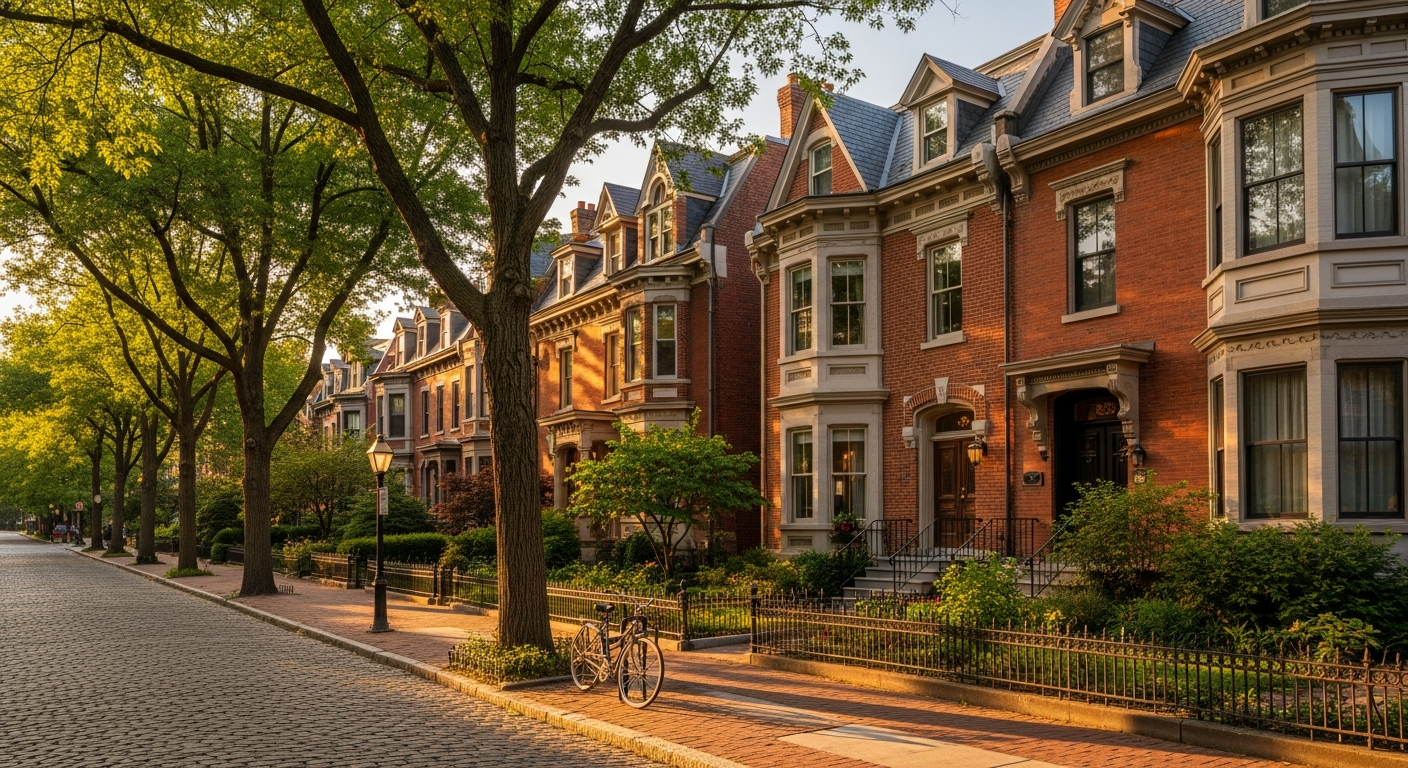
Historic districts have a way of stopping people in their tracks. The architecture is distinct, the streets feel lived-in and human-scaled, and the homes carry a presence that newer construction rarely matches. For co-buyers, these neighborhoods can also offer something practical: price points that are sometimes more accessible than you'd expect, given the character and location on offer.
But co-buying a home in a historic district adds a layer of complexity that you have to take seriously before you close. The designation itself creates rules. Those rules affect what you can do to the property, how you make decisions as co-owners, and how your lender and appraiser will evaluate the home. None of this is a dealbreaker. It's just terrain you need to navigate with your eyes open.
What Historic District Designation Actually Means
Historic district designation can come from two different sources, and it matters which one applies to your property.
National Register of Historic Places. The National Register is a federal program administered by the National Park Service. Listing on the National Register is largely honorary for private homeowners. It doesn't restrict what you can do to your property, but it does make certain tax incentives available. Many people assume federal listing means federal control over their renovations. It doesn't.
Local historic district designation. This is the one with real regulatory teeth. Local historic districts are created by city or county governments, typically through historic preservation ordinances. When your property sits inside a locally designated historic district, you are subject to design review before you can make changes to the exterior of the home. In many jurisdictions, this review is carried out by a Historic Preservation Commission (sometimes called an Architectural Review Board or similar). You need their approval before you alter windows, doors, siding, rooflines, porches, fences, or anything else visible from a public way.
Some properties carry both designations. Some carry only one. A handful sit in local historic districts without any federal recognition. When you're evaluating a specific address, you need to confirm which designations apply and pull the relevant local ordinance to understand what that district's rules actually say.
How Historic Designation Affects What You Can Do to the Home
For co-owners thinking about renovations, the core principle of local historic district regulation is the concept of "visual compatibility." Any change to the exterior of your home has to be visually compatible with the historic character of the district. What that means in practice varies by jurisdiction, but some patterns are consistent across most historic preservation programs.
What typically requires review and approval:
- Replacing windows (most districts require preservation or like-for-like replacement of original wood windows; vinyl replacements are often denied)
- Changing exterior doors or adding storm doors that alter the historic character
- Removing or altering original siding, trim, or decorative elements
- Adding or removing a porch
- Building an addition visible from the street
- Replacing roofing materials with a different type or profile
- Installing solar panels on a front-facing roof slope (this varies widely by jurisdiction)
- Adding a fence, outbuilding, or garage
What typically does not require review:
- Interior renovations of any kind
- Repainting in an approved color (some districts have pre-approved palettes; others just require you to notify)
- Routine maintenance and repairs that use like-for-like materials
- Rear or side additions that are not visible from a public right-of-way, depending on the district
The approval process itself usually involves submitting an application with photos, material samples, and plans, then waiting for the Historic Preservation Commission to review them, often at a scheduled public meeting. Timelines range from a few weeks to a few months. Emergency repairs are typically handled on an expedited basis.
Violations can be costly. Unpermitted exterior changes in a historic district can result in fines, mandatory restoration to the original condition, and complications when you go to sell.
How Designation Affects Co-Owner Decision-Making
For co-buyers, historic district rules add an important dimension to how you govern the property together. You're not just deciding what you want to do. You're deciding what you're allowed to do, and working within a process that is slower and less certain than a standard renovation.
This has real implications for your co-ownership agreement.
Capital improvement decisions take longer. If one co-owner wants to replace the windows and the other isn't sure it's worth pursuing given the approval process, that disagreement needs a framework. Your co-ownership agreement should specify how capital improvement decisions are made, including who initiates the review process, how costs are shared, and what happens if a planned improvement is denied.
You need a shared maintenance standard. Historic districts often require that exterior elements be maintained in good repair. If the paint is peeling or the porch is deteriorating, you may be subject to a notice of violation. Your agreement should address who is responsible for monitoring the exterior condition and how deferred maintenance decisions are made.
Renovation vetoes have more consequence. In a standard co-owned home, one co-owner vetoing a renovation is a financial and personal disagreement. In a historic district, the renovation might also require external approval, which means the disagreement can have timing and regulatory consequences. Co-owners should think carefully about the approval threshold they set for historic-district-specific improvements and build in a process for resolving deadlocks.
Budget for contingencies. Historic preservation commissions can approve, deny, or approve with conditions. A project you budgeted at one cost may come back requiring more expensive materials to meet the district's standards. Your shared reserve fund should account for this uncertainty.
If you're using Rhome's co-ownership structure, the co-ownership agreement already addresses capital improvements and decision-making. In a historic district, you'll want to make sure those provisions are drafted with the approval process in mind.
Historic Tax Credits: What Co-Owners Should Know
One of the genuine advantages of owning a historic property is access to tax incentives for qualified rehabilitation work. The two most relevant programs for residential co-buyers are the federal Historic Tax Credit and state-level programs.
The Federal Historic Tax Credit (HTC). The federal program, administered through the National Park Service and IRS, provides a 20% tax credit for qualified rehabilitation expenditures on certified historic structures. The significant limitation for residential co-buyers is that the federal Historic Tax Credit is not available for properties used as a personal residence. It applies to income-producing properties: commercial buildings, rental properties, and mixed-use structures.
If you and your co-owners plan to use the home as your primary residence, the federal HTC is not in play for your renovation spending.
State historic tax credits. Many states have their own historic tax credit programs, and some of them do cover owner-occupied residences. Programs vary significantly by state. Some offer credits of 15 to 25 percent on qualified rehabilitation expenses. Some require the property to be listed on the National Register or a state register of historic places. Some have income caps or per-property expenditure limits. A few states have programs specifically designed for homeowners, not investors.
You'll need to check your specific state's preservation office for current program details, as these programs are subject to legislative changes and funding availability. The National Trust for Historic Preservation maintains a database of state programs that is worth reviewing early in your search.
Property tax abatements. Many local jurisdictions also offer property tax abatements or freezes for owners who rehabilitate historic properties. These are often administered separately from state programs and may apply even when you don't qualify for tax credits. Ask your local preservation office or county assessor about what's available in the specific district you're considering.
For co-owners, tax credits and abatements need to be factored into how you split and track shared expenses, since the benefit flows to the owners who paid for the qualified work.
FHA Appraisals in Historic Districts
If any of your co-owners plan to use FHA financing, you'll want to understand how FHA appraisals interact with historic district properties.
FHA appraisers are required to flag any property condition that poses a health, safety, or structural risk. Older homes in historic districts are more likely to have the kinds of conditions FHA looks at carefully: peeling lead paint, older electrical systems, galvanized plumbing, knob-and-tube wiring, deteriorating rooflines, and deferred exterior maintenance.
The challenge in a historic district is that the obvious fix for some of these conditions may require Historic Preservation Commission approval, which takes time. An FHA appraisal that comes back with required repairs, combined with a historic district that requires design review before those repairs can be made, can create a real scheduling problem in your purchase timeline.
Practical ways to manage this:
- Get a thorough inspection before making an offer, with special attention to the systems and exterior elements FHA appraisers commonly flag
- Ask the seller for documentation of any approvals for past work, to confirm prior changes were permitted
- Build adequate time into your closing timeline to accommodate both the appraisal process and any pre-closing repairs
- Talk to your lender early about whether the property is likely to need FHA repair conditions, and whether conventional financing might be a cleaner path for this particular home
Conventional loans generally have more flexible property condition standards than FHA, which can simplify the purchase process in historic districts. Your co-owners' individual credit profiles and down payment capacity will determine what financing options are actually on the table.
The Real Advantages of Co-Buying in a Historic District
With all the complexity laid out, it's worth being clear about what makes historic district co-ownership genuinely attractive.
Price accessibility. Historic homes often need work, and work creates hesitation in buyers. When you co-buy, you pool resources for both the down payment and the renovation budget. A property that feels out of reach for a single buyer can become financially feasible when two or three people share the cost. Many of the most appealing historic neighborhoods have prices that are still meaningfully below equivalent new construction.
Built-in character. Historic homes have architectural features that are expensive or impossible to replicate: original hardwood floors, plaster walls, built-in cabinetry, transomed doorways, craftsman details. Buying into that is a different experience than buying into a neighborhood built in the last twenty years.
Neighborhood stability. Historic district designation, almost by definition, comes with strong community identity and an organized preservation infrastructure. These neighborhoods tend to attract residents who are committed to the area long-term. That kind of social fabric matters for quality of life and, over time, for property values.
Appreciation in strong markets. Designated historic districts in walkable, established neighborhoods have shown strong long-term appreciation in many metropolitan areas. The supply of historic properties is constrained by definition, and demand from buyers who value architecture and neighborhood character tends to be durable.
Renovation discipline. For some co-owners, the oversight structure of a historic district is actually welcome. It prevents any one co-owner from making an impulsive exterior change that the others regret. The need to go through a formal approval process creates a natural checkpoint.
Questions to Ask Before You Co-Buy in a Historic District
Before you make an offer on a historic district property with co-owners, work through these questions together and with your real estate attorney.
- Which designation applies, and what does the local ordinance actually say? Pull the specific ordinance, not a summary. Know what triggers review and what the approval standards are.
- What's the Historic Preservation Commission's track record in this district? Talk to neighbors or local preservation advocates. Some HPCs are collaborative and practical. Others are slow or rigid. That affects your renovation planning.
- What exterior work has already been done, and was it permitted? Unpermitted prior work can become your problem at sale or if the city does a survey of the district.
- Are any state or local tax incentive programs available for this property and this type of work? Don't assume. Check before you buy, since some programs require pre-approval before work begins.
- How will your co-ownership agreement handle renovations that require historic approval? Write the decision-making process, cost-sharing, and contingency handling into the agreement before you close.
- What's the FHA appraisal exposure, and how does your financing plan account for it? Know your lender's property condition requirements before the appraisal, not after.
- Is there an active neighborhood preservation organization? These groups are often the best source of practical information about what the HPC approves, what contractors have experience with historic work in the area, and what pitfalls other owners have encountered.
FAQ
See faqItems below.

